Conventional
The starting point for most W-2 buyers — fixed and adjustable options for purchase and refinance, including the high-balance limits sized for Santa Clara County. Usually the benchmark every other program gets measured against.
Independent Mortgage Broker · San Jose, California
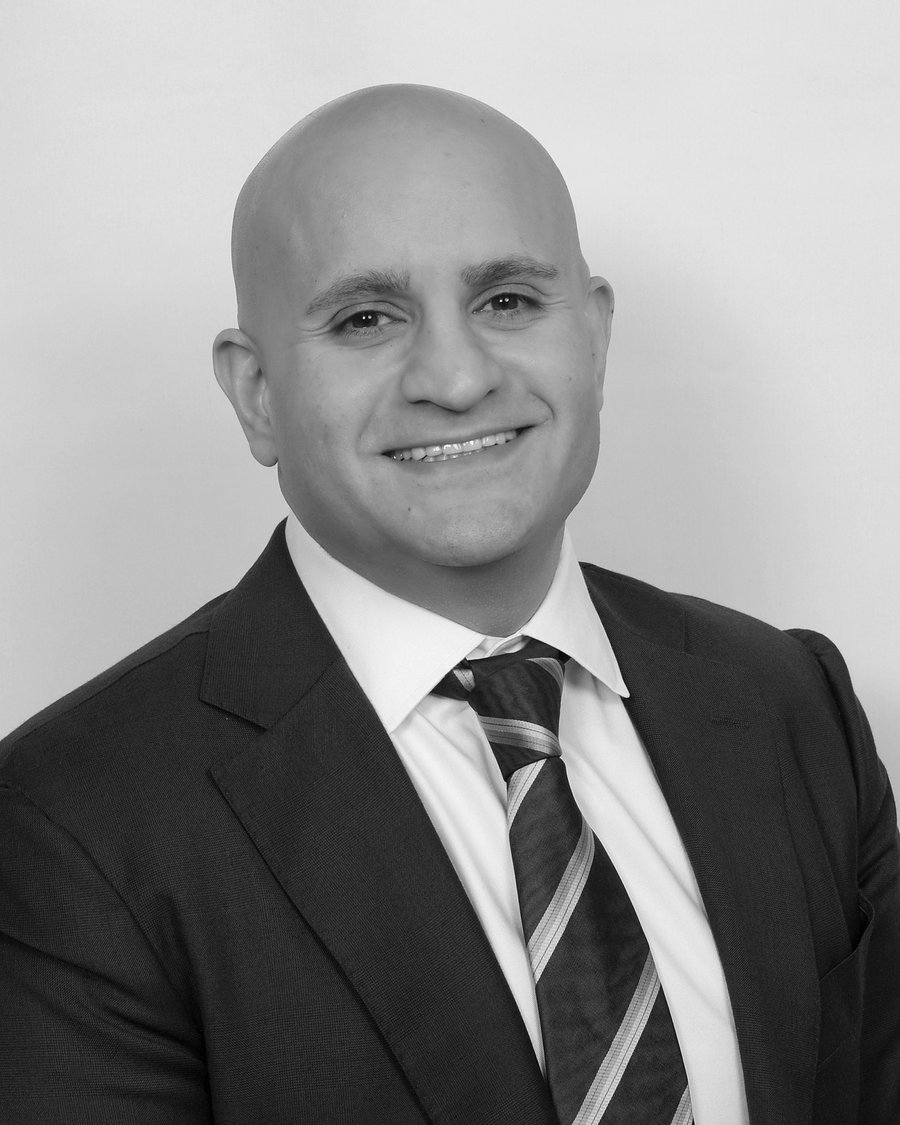
No one should sign a mortgage they don't fully understand. First home or complex jumbo file, I walk you through every option — as many times as it takes — until the right choice is obvious to you, not just to me.
or write to mehdi@mehdikousha.com
NMLS #633059 · CA DRE #01470042 · Reliance Bay Funding NMLS #348792
Loan Programs
Half my clients are buying their first home. The other half bring files that banks struggle with. Both get the same thing: every option on the table, explained until it's clear.
The starting point for most W-2 buyers — fixed and adjustable options for purchase and refinance, including the high-balance limits sized for Santa Clara County. Usually the benchmark every other program gets measured against.
Around here, prices clear the conforming limit long before the house looks expensive. Financing above those limits for Silicon Valley price points — including qualification on RSU and stock-based compensation, on select programs for qualified borrowers.
Your returns are written to lower your tax bill, which is exactly what makes them a poor description of your income. Business owners and 1099 earners qualified on bank statements, P&L, or assets instead — select programs, qualified borrowers.
Every financed property makes the next one harder to qualify for on personal income. Purchase and cash-out financing for rentals, including DSCR programs that qualify on the property's own income rather than your tax returns.
The part nobody explains is what any of it actually means. Low down payment options where they fit, plus a walkthrough of the whole process in order, at whatever pace you need. No question is too basic — that is rather the point.
If your first mortgage is in the threes, there is no reason to give it up. A second lien sits behind that loan and leaves its rate exactly where it is — lines up to 90% combined loan-to-value on select programs for qualified borrowers.
Explore home equity →Calculators
Set any interest rate you like and watch the figures move. These are modeling tools — your actual rate and terms depend on your profile, property, and program.
Set by you, for modeling — not an advertised rate or offer.
Car loans, student loans, minimum card payments — not rent.
Set by you, for modeling — not an advertised rate or offer.
For illustration and education only. Figures are estimates and do not constitute a quote, rate lock, offer, or commitment to lend. The interest rate is set by you for modeling purposes and is not an advertised rate; actual rates, payments, and qualifying amounts depend on your credit profile, property, and program, and not all applicants will qualify. NMLS #633059.
Home Equity
Many Bay Area homeowners are sitting on a low first-mortgage rate and a large amount of equity. A HELOC or home equity loan sits behind your existing loan, so that rate stays exactly where it is.
Lines of credit and fixed home equity loans for renovations, consolidation, education, or investment — with combined loan-to-value up to 90% on select programs for qualified borrowers. I'm approved with both traditional and fintech home equity lenders, so we can compare speed, cost, and structure side by side. Some approvals move in days rather than weeks on select programs.
Discuss your equity →Equity Estimator
A HELOC is a revolving line of credit secured by your home — you draw what you need, when you need it, typically at a variable rate. A home equity loan delivers one lump sum, usually at a fixed rate with fixed payments. Both sit behind your existing first mortgage, so the rate on your first loan stays untouched.
Most programs lend up to 80% of your home's value combined across all loans (CLTV); select programs go to 90% for qualified borrowers. For example, on a $1.5M home with a $600K balance, 80% CLTV would make up to $600K available. Program, credit profile, and property all affect the final number.
Broadly: meaningful equity in the home, a solid credit profile, and documented ability to repay. Requirements vary by program — and self-employed borrowers have options here too, including alternative documentation on select programs.
Sometimes. Under current federal rules, interest may be deductible when the funds are used to buy, build, or substantially improve the home securing the line, subject to limits. I'm not a tax advisor — please confirm how the rules apply to you with a tax professional.
Home equity lines of credit and home equity loans are secured by your home; failure to repay may result in the loss of your home. Estimates above are illustrative only — maximum line amounts depend on program, credit profile, and property.
Client Reviews
He is an expert in home loans and got us a very good loan.Client review · Read on Yelp
Excellent follow-up and follow-through.Client recommendation · Read on LinkedIn
Rated 5.0 by clients on Zillow — you can also read reviews on Yelp and LinkedIn.
About
I spent the first chapters of my career inside major banks — senior lending leadership roles at PenFed, Citigroup, and Bank of America — approving loans, and watching good borrowers get declined for reasons that had nothing to do with their ability to repay. Going independent as a broker under Reliance Bay Funding meant I could finally match each client to the lender and program actually built for their situation, instead of forcing every file through one bank's box.
Today my practice splits down the middle. Half is first-time buyers in San Jose, Morgan Hill, and Gilroy who want the process explained properly — and I will explain it as many times as it takes. The other half is complex files: self-employed borrowers, tech professionals with RSU and stock compensation, jumbo loans at Silicon Valley price points, investors, and foreign nationals. Most brokers pick one lane. I've never seen a reason to.
Two things I take unusually seriously: financial literacy — you should leave every conversation understanding your loan better than when you arrived — and wire-fraud protection, because a mortgage is the largest transfer of money most people ever make and it deserves that vigilance. I serve clients in English and Farsi.
How We Work
01
Twenty to thirty minutes on your goals, numbers, and timeline. No credit pull until it actually helps you.
02
Documentation mapped to your profile — W-2, self-employed, or RSU — and a pre-approval that holds up with listing agents.
03
Programs and lenders compared side by side, trade-offs included, until the choice is obvious to you.
04
I manage underwriting conditions and deadlines. You sign understanding every page you're signing.
Questions
Yes. My office is in Willow Glen, and most of my clients are buying or refinancing in San Jose, Morgan Hill, Gilroy, and the surrounding Bay Area. I'm licensed to originate home loans anywhere in California (NMLS #633059).
Yes — first-time buyers are half of my practice. I walk you through the entire process step by step, explain every document before you sign it, and cover low down payment options where they fit. No question is too basic.
Yes. I work with clients in both English and Farsi, from the first conversation through closing.
A bank can only offer its own menu. As a broker I take one application and shop it across many wholesale lenders — including programs banks rarely carry, like bank statement loans, DSCR, and a wider jumbo shelf. After twenty years inside major banks, I also know exactly where they say no, and what to do about it.
Usually yes — just not through a conventional loan. Bank statement programs qualify you on 12 or 24 months of deposits; others use a CPA-prepared P&L, or assets alone. The write-offs that lower your tax bill stop counting against you. These are select programs for qualified borrowers and they generally price higher than conventional, which is the trade-off worth walking through before you apply anywhere.
Some will, on select programs. What they typically want to see is a vesting history going back a couple of years, evidence the grants continue, and a stock liquid enough for their comfort. How much of it counts varies by lender — which is exactly why it is worth comparing before you write an offer rather than after.
Often yes, but only if something actually changes. A decline is usually one lender’s guidelines rather than the whole market, so the first thing I want to see is the specific reason you were turned down. Sometimes the answer is a different lender, sometimes a different program, and sometimes it is ninety days and one thing fixed. I will tell you which one it is.
Thirty days is a normal purchase timeline and a clean W-2 file can move faster. Self-employed and jumbo files usually want more room — the documentation takes longer to assemble and underwriting takes longer to read. It depends on the lender, the property, and how fast conditions come back, so I would rather give you a realistic timeline at the start than an optimistic one.
Contact
Whether it's your first mortgage or your tenth property, the first conversation costs nothing and commits you to nothing — and you'll leave it understanding your options better.
Conversations available in English and Farsi. گفتوگو به زبان فارسی.